If Tesla’s Robotaxi Miles Keep Compounding at 20% a Week, the Math Gets Interesting Fast
Support CleanTechnica’s work through a Substack subscription, on Patreon, or on Stripe. Help us produce all of the high-quality, original content we publish week after week despite the challenges of content-scraping AI, antisocial media, inflation, and other hurdles.
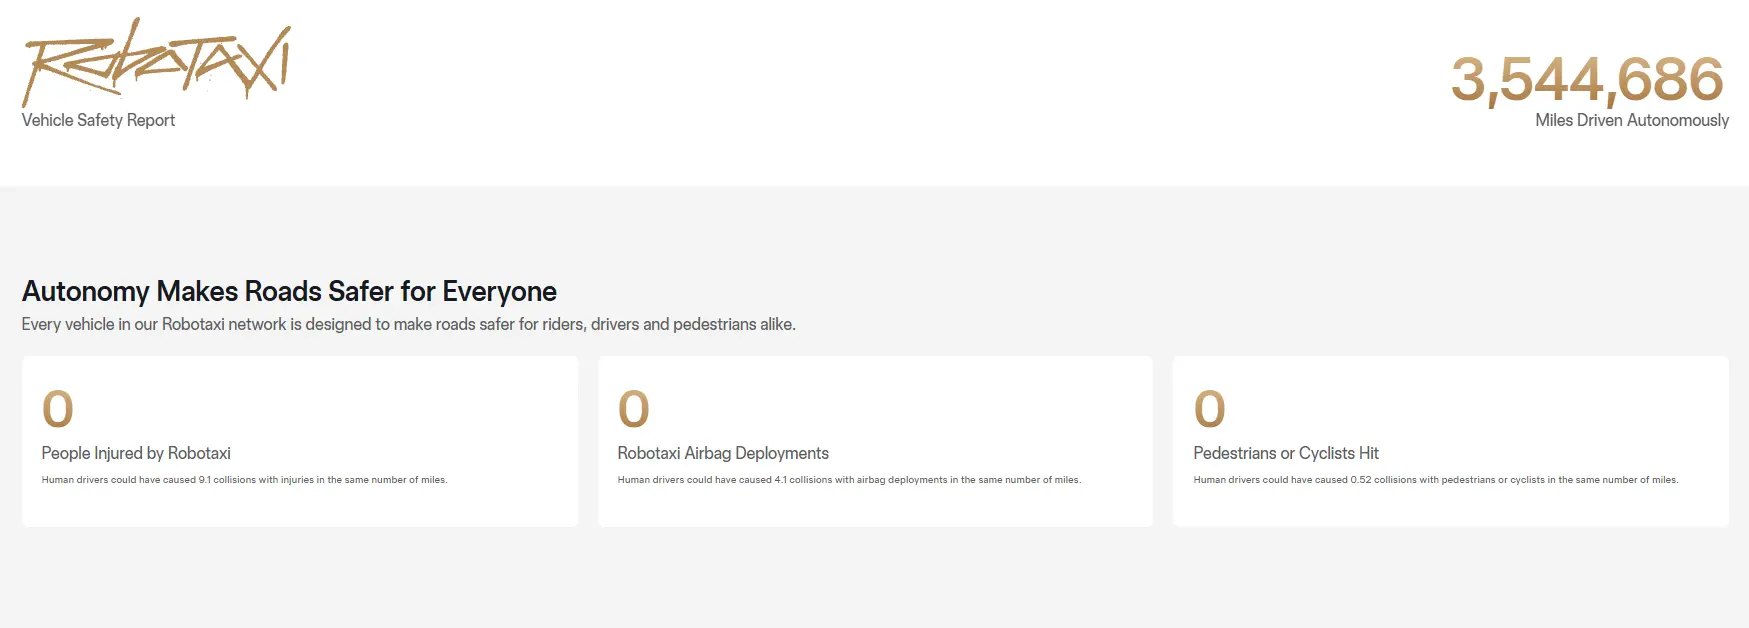
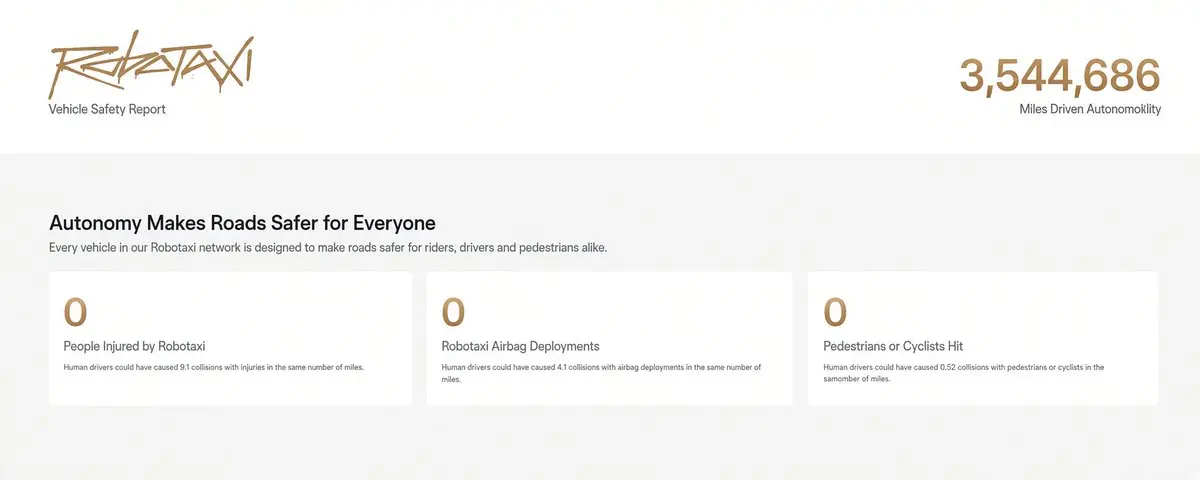
Tesla just passed Waymo in Austin in weekly driverless miles. If its recent 20% weekly growth holds, it passes Waymo nationally in roughly 11 weeks and is doing the volume of Uber + Lyft across three Texas metros by mid-February.
The accumulating unsupervised miles are already large enough to start answering the safety question versus humans and versus Waymo. That has implications for whether LiDAR is actually required.
I noted in my Q3 earnings summary that Tesla’s unsupervised robotaxi miles jumped from 250,000 last quarter to about 1.7 million, and then the same day the company said they were already at 3.3 million. That implies roughly 20% weekly growth on the recent run. I want to take that number seriously for a limited window and see where it goes relative to Waymo and to the actual ride-hail market in the Texas cities where Tesla is already operating. Then I’ll draw some conclusions.
It looks like Tesla has already surpassed Waymo in Austin. Next, let’s look at what it would take for them to pass Waymo nationally and for them to start to eat into Uber and Lyft marketshare.
The Math Through the Crossovers
Tesla Unsupervised Weekly Miles Projection (20% compound weekly growth from current national unsupervised miles/week):
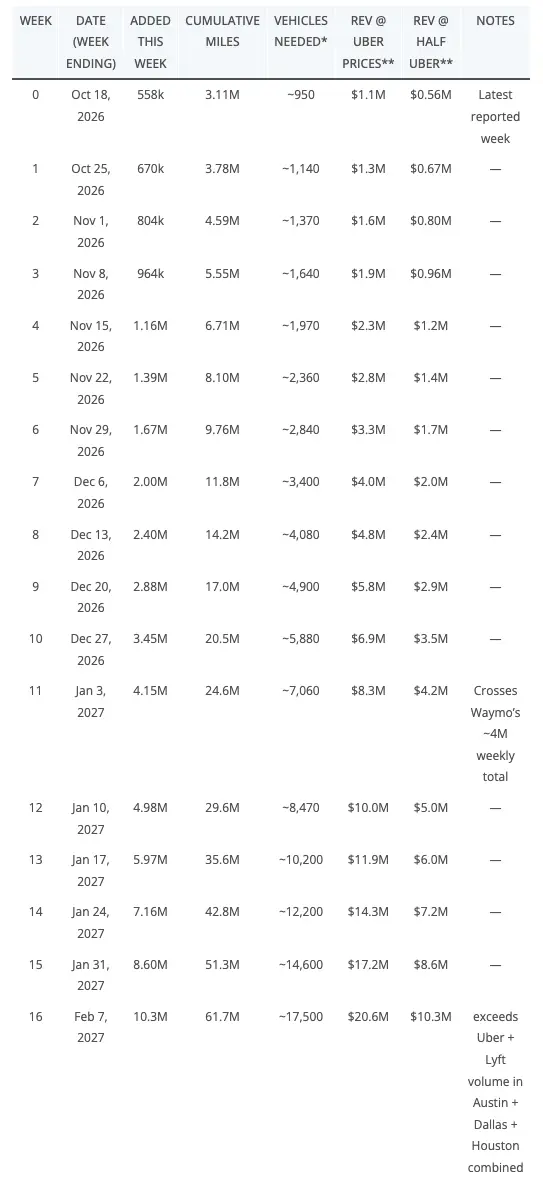
From 558K/week, the rate crosses Waymo’s recent ~4 million weekly national total in around week 11. By week 16, the weekly rate would be roughly 10 million miles. That is the point where Tesla’s weekly volume would exceed half the current Uber + Lyft volume in Austin, Dallas, and Houston combined.
How Fast Has Waymo Actually Been Growing?
Waymo’s recent numbers make the crossover more striking. Through the end of June 2026, the company had logged 271.3 million cumulative rider-only miles. In Q2 2026, it added only about 50.7 million miles, versus 49.9 million in Q1—sequential growth of roughly 1.6%. Earlier quarters in 2025 had seen quarterly growth of 15% or better. City-level data shows the same cooling: Phoenix has posted two straight quarterly declines, Austin’s quarter-over-quarter growth fell from over 100% early in 2025 to about 4% in Q2 2026, Los Angeles was near 9%, and San Francisco was near 13%. Atlanta grew faster off a small base, but the overall picture is a large installed base whose percentage growth has slowed sharply. Even if Waymo regains its quarterly growth of 15%, that is dramatically lower than the 970% quarterly growth implied in my table above.
Austin, Dallas, and Houston: The Realistic Near-Term Market
The Austin metro area has roughly 2.4–2.6 million people and about 45 million vehicle-miles traveled per day (roughly 315 million per week). Waymo’s recent weekly rate there is about 400,000 miles; Tesla’s most recent tracked week in Austin was about 438,000 miles. Both are still tiny fractions of total driving. Dallas–Fort Worth (~5.7 million people, ~157 million daily VMT) and Houston (~5.9 million people, ~144 million daily VMT) are substantially larger. Tesla’s current Dallas zone is already bigger than its early Austin footprint (roughly 81 square miles) and has logged over 600,000 cumulative unsupervised miles. Houston remains smaller: about 25 square miles and roughly 226,000 cumulative miles. Waymo is present in both cities with public service. Estimated weekly Uber + Lyft miles (combined, paid passenger miles only):
-
- Austin: 1.5–2.5 million
-
- Dallas–Fort Worth: 4–6 million
-
- Houston: 4–6 million
-
- Three-city total: roughly 10–14 million
Pricing Changes the Addressable Market
If Tesla prices at roughly half of Uber, the relevant market is no longer limited to ride-hail substitution. Personal driving in the three metros is hundreds of millions of miles per week. Even a 1–2% shift of trips that are currently driven privately becomes several million additional weekly miles once the per-mile cost drops well below the fully loaded cost of owning and operating a personal car for many trips. Some off-peak or transfer-heavy transit trips (CapMetro, DART, Metro) become competitive as well.
The practical near-to-medium-term opportunity in just these three cities is therefore larger than the 5–7 million weekly ride-hail slice—potentially 10–20+ million once personal-trip substitution appears. The 16-week 20% compounding path already reaches ~10 million weekly miles. That clears half the current Uber + Lyft total in the three cities and leaves room for the start of personal-trip substitution, provided the Dallas and Houston geofences expand enough and the fleet scales to absorb the demand. Sustaining 20% weekly for 16 straight weeks while also enlarging the service areas is the operational question, not the demand question. Price becomes the demand lever once the vehicles and the geofences are large enough.
What Could Go Wrong
The arithmetic is clean. The path from here is not.
First, the 20% weekly rate is a launch rate observed while the absolute numbers are still small and concentrated in one city. Sustaining it for 16 weeks means the weekly addition itself has to keep growing. That requires either rapid vehicle deployment or a sharp rise in utilization per vehicle. Both get harder as the fleet expands: charging infrastructure has to keep pace, maintenance capacity has to scale, and local regulators have to approve larger operating zones. A single high-profile incident that triggers a pause in any of the three cities would flatten the curve immediately.
Second, geofence expansion is not automatic. Dallas and Houston currently operate in far smaller zones than Austin. Moving them to Austin-scale coverage involves mapping, local permits, and public acceptance. Any delay pushes the volume absorption problem into 2027.
Third, utilization can fall even if the fleet grows. If vehicles spend more time empty, charging, or waiting for demand that has not yet shifted from personal cars, the miles per vehicle drop and the required fleet size rises.
Fourth, pricing at half of Uber’s price assumes Tesla can still cover its costs at that level. If insurance, remote assistance, or cleaning costs run higher than expected, the price cut either shrinks or disappears, and the personal-trip substitution story weakens.
None of these are fatal. They are the ordinary constraints that turn an early exponential into an S-curve. The 16-week path clears the math for a material position relative to current ride-hail in three Texas cities. Whether the vehicles, the zones, and the operations arrive on that schedule is the open question.
My Read
Tesla is not primarily trying to out-mile Waymo on a percentage basis. It is trying to show that the unit economics of an unsupervised Cybercab (or Model Y) can work at scale, with revenue expected to become noticeable in 2027. The recent 20% weekly growth is the clearest signal yet that the software has cleared an internal quality bar in the cities where it is running—and the accumulating unsupervised miles already provide a meaningful basis to compare safety outcomes against both human drivers and Waymo. If Tesla’s rate of incidents continues to hold as the fleet scales, it undercuts the long-standing claim that LiDAR is required to operate more safely than humans.
Superior results relative to Waymo would further suggest that more capable software matters more than simply adding sensors to less sophisticated systems. Whether the same growth rate can be sustained long enough for the weekly total to pass Waymo’s, and whether Dallas and Houston can be brought up to Austin-like coverage in the next four months, are the next two questions. History suggests at least one constraint appears before the curve stays perfectly exponential, but the arithmetic no longer requires an absurd number of cities or an impossible fleet to become material relative to existing ride-hail. Any progress they make in Florida (my home state) in Miami, Orlando, Tampa, and Jacksonville is a bonus for the short term, but they need to continue their growth going forward.
If you want to take advantage of my Tesla referral link to get up three months Full Self Driving, here’s the link: https://ts.la/paul92237 — but if another owner helped you more, please use their link instead of mine. Disclosure: I am a shareholder in Tesla and XPeng. I offer no investment advice of any sort.
Sign up for CleanTechnica’s Weekly Substack for Zach and Scott’s in-depth analyses and high level summaries, sign up for our daily newsletter, and follow us on Google News!
Have a tip for CleanTechnica? Want to advertise? Want to suggest a guest for our CleanTech Talk podcast? Contact us here.
Sign up for our daily newsletter for 10–15 new cleantech stories a day. Or sign up for our weekly one on top stories of the week if daily is too frequent.
CleanTechnica uses affiliate links. See our policy here.
CleanTechnica’s Comment Policy